


Tile Roofing | South Florida
Could Your Tile Roof Lower Your Florida Home Insurance?
A tile roof may qualify for a windstorm credit, but the result depends on your roof, its installation, and your insurer. Here is what to know, and how we can help you find out.
By Jonathan Rodriguez · Published October 27, 2026
Short answer: will a tile roof lower my home insurance Florida wind mitigation credits? A tile roof can earn a windstorm credit when its covering, attachment, and related features meet the insurer’s criteria. It is not automatic. Insurers look at how the roof is built and attached, not just the material. This guide explains what the inspection checks, how insurers use the results, and how roof timing affects the outcome.
Understanding Wind Mitigation in Florida
A wind mitigation inspection is a documented check of features that affect how a home is likely to hold up in a windstorm. The inspector records items such as the roof covering, how the roof is attached, and how openings are protected. The results go on a state form that insurers use for windstorm discounts. Under Fla. Stat. § 627.711, the Financial Services Commission develops a uniform mitigation verification inspection form that all insurers must use. The discount follows the home’s physical features. It does not follow the homeowner’s claims history alone. Insurers must accept a valid form signed by authorized inspectors, yet Fla. Stat. § 627.711(9) lets an insurer, at its own cost, require independent verification of a mitigation form submitted by a policyholder, a policyholder’s agent, or an authorized mitigation inspector or inspection company before accepting it; the statute, however, does not require independent verification or reinspection of such a form sent to Citizens Property Insurance Corporation, absent material changes, when it was signed by an authorized mitigation inspector and verified by a quality assurance program the corporation approved before submission, so the signed form is not always the final word.
If a renewal notice or storm damage has you reviewing a tile roof for someone you love, our team can walk through those details with you. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What Are Wind Mitigation Credits in Florida?
A wind mitigation credit is a premium reduction an insurer may apply when inspected features meet its criteria. Under Fla. Stat. § 627.0629, a residential property insurance rate filing must include actuarially reasonable discounts or credits for features that reduce windstorm loss. Each insurer files its own rates. That means credit amounts and rules can differ from one company to the next. The same home can get different results with different carriers. Starting October 1, 2023, each insurer subject to the requirements must describe its hurricane mitigation discounts on its website, accessible on or through a hyperlink located on the home page or the primary page for property insurance policyholders or applicants. Homeowners usually submit the official form to an insurance agent, as the Office of Insurance Regulation explains. The credit relates to windstorm coverage on the policy.
Does a Tile Roof Qualify for the Discount?
A tile roof can earn credit when its covering, attachment, and related features meet the insurer’s criteria. The statute lists roof covering performance and roof strength among the features that qualify, so tile is not excluded by its material. The inspector looks at the covering type and how it attaches to the roof deck. The covering alone doesn’t decide the result. Tile roofing work in South Florida depends on the roof structure, the type of tile, and site conditions, so a professional assessment helps determine the right approach. Whether a specific tile roof earns credit depends on the facts: the installation, the deck, and the paperwork you can produce.
What a Wind Mitigation Inspection Checks
The inspection records the features that affect windstorm performance. Common items include roof covering type, roof deck attachment, roof-to-wall connection, roof shape, opening protection, and secondary water resistance. The inspector notes each item, often with photos. Clear notes make it easier for the insurer to confirm each feature. The completed form is the document homeowners typically share with their insurer. The Florida DFS consumer guide covers the inspection itself, qualified inspectors, documentation requirements, and roof-related mitigation features. Read it before you request the inspection so you know what the form asks for.
Key Roof Features That Affect Insurance Rates
Roof shape, roof-to-wall connections, and opening protection are three features that matter most in this inspection. Florida’s building rules name roof shape as a factor in windstorm design. For homes with both hip and gable roof ends, Fla. Stat. § 553.844 gives priority to retrofitting gable-end connections unless the width of the hip is more than 1.5 times greater than the width of the gable end. For existing buildings that are not otherwise required to comply with the Florida Building Code for new construction, Fla. Stat. § 553.844 directs the Florida Building Commission to provide alternate, lower-cost means of improving roof-to-wall connections so that the cost of such improvements does not exceed approximately 15 percent of the cost of reroofing. Whether a particular roof replacement must include roof-to-wall connections at all depends on further conditions in the statute, including the type of structure, whether it is in the wind-borne debris region, and its insured or assessed value. Opening protection covers windows, doors, and skylights. Impact-rated openings are one way to address that item. Our impact windows and impact doors pages cover those options in more detail.
Why Insurers Offer Discounts for Mitigated Roofs
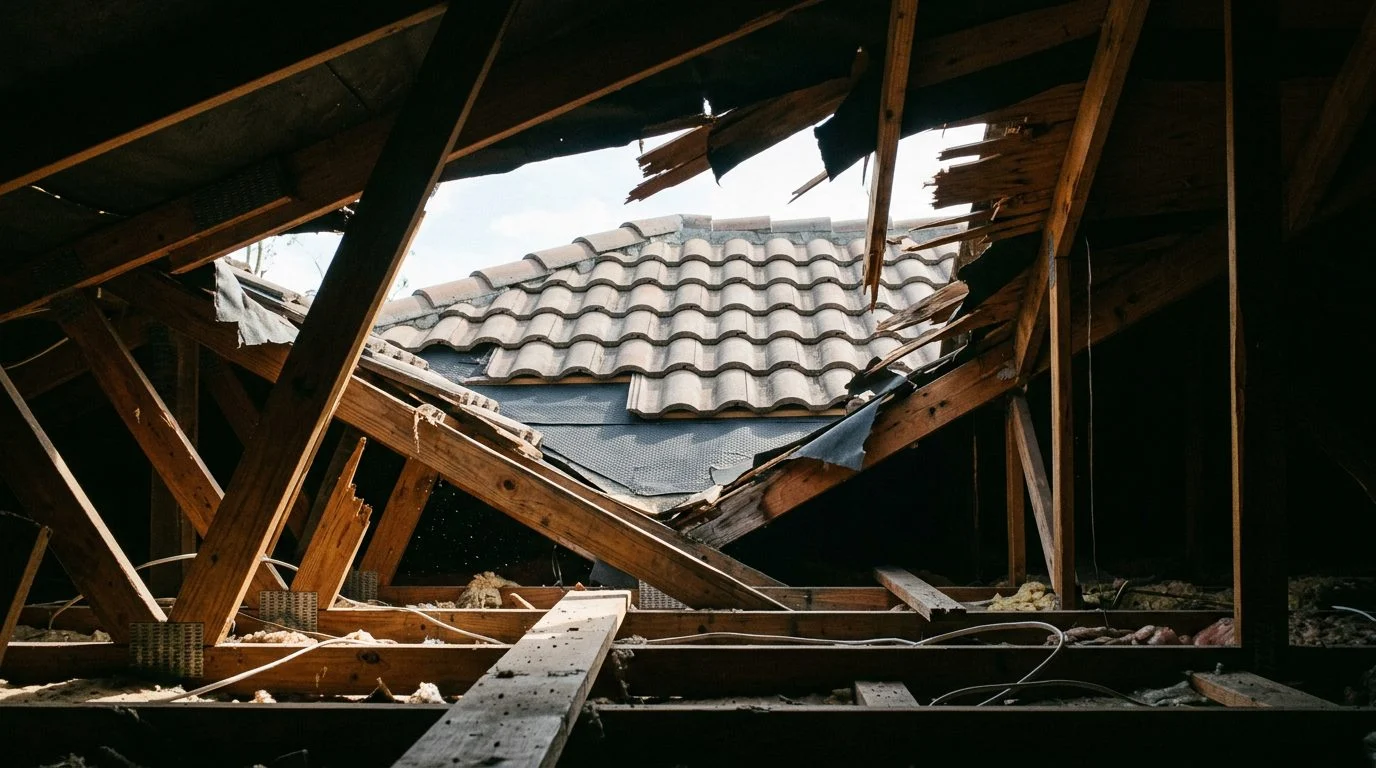
Insurers offer these credits because Florida law points them toward rewarding windstorm-resistant construction. The Legislature found that the Florida Building Code has demonstrated effectiveness in reducing property damage to buildings built under its requirements, per Fla. Stat. § 553.844. The insurance statute says insurers should provide savings to consumers who install windstorm mitigation techniques. That is the reason behind the credit structure. It does not promise any individual result. A roof damaged in a storm can change the picture. If the covering has storm damage or leaks after a storm, the roof as inspected may differ from its original build. Our guide on what to look for after a storm can help you check for signs of damage.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Timing a Wind Mitigation Inspection With a Roof Replacement
A roof replacement changes the roof features the inspector will record, so timing matters. For an existing roofing system or roof section that was built, repaired, or replaced to comply with the 2007 Florida Building Code or a later edition, when 25 percent or more of that system or section is repaired, replaced, or recovered, only the repaired, replaced, or recovered portion must be constructed in accordance with the Florida Building Code currently applicable. Keep the permit records, product documentation, and installation details from a new tile roof. The inspector and the insurer may both ask for them. Solar equipment on a tile roof can affect roof access and documentation. Note where panels attach and who installed them. Our solar panels on tile roofs guidance covers the Florida details.
Where to Start if This Is Not Your Decision
Many people read about this topic for a parent, a relative, or a home they are buying. The renewal notice or storm damage was often not their choice. Bring these items to the conversation: the roof covering type, the year it was installed, the attachment details, and any storm or repair history.
Frequently asked questions
Does a tile roof lower home insurance in Florida?
A tile roof can earn a windstorm credit when its covering and attachment meet the insurer’s criteria. The credit is not guaranteed.
Will a tile roof lower my home insurance Florida wind mitigation credit?
It depends on the facts, including the installation, the roof deck, and the records you have. Each insurer sets its own credit rules.
Who usually submits the wind mitigation form?
Homeowners usually submit the official form to their insurance agent to request the discount.
Does replacing a roof change wind mitigation results?
Yes, because the new roof’s features are what the inspector records. Keep the permit and product records.
Talk With Our Team About Your Tile Roof
The answer turns on your roof’s actual construction and its paperwork. Our team can review those details with you, starting with the covering type, the install date, and the attachment details. If you have a storm or repair history, share that too. Our South Florida tile roofing page covers the full range of tile roofing services we offer.
If a renewal notice or storm damage has you reviewing a tile roof for someone you love, you don’t have to sort out the details alone. Our initial consultation is free, confidential, and comes with no obligation to continue. Contact our team to start that conversation.
What Shapes Your Insurance Credit
Covering and attachment
Insurers look at how the tiles are secured to the roof deck and whether the installation meets their wind-resistance criteria.
Installation records
Permits, inspection reports, and product documentation help show how the roof was built and what it can withstand.
Your insurer's rules
Each company applies its own standards for windstorm credits, so the same roof can be treated differently by different carriers.
Upgrades that matter
Impact windows, impact doors, and a well-maintained roof can all work together to strengthen the home's wind profile.
Don't Assume a Discount
Having a tile roof does not automatically lower your premium. Ask your insurer what documentation it needs before you expect any credit, and keep your roofing records in one place.
How to Prepare Before You Call Your Insurer
Gather your roof records
Collect permits, installation invoices, product labels, and any inspection reports for your tile or metal roof.
Note your roof's age and condition
Record when the roof was installed and any repairs or replacements since then.
Ask about wind mitigation
Request a wind mitigation inspection and ask which features your insurer will credit.
Plan for upgrades
If your roof or openings need work, a roof repair, roof replacement, or impact window and door project may improve your home's wind resistance.


