


Tile Roofing & Roof Replacement | South Florida
Insurer Says Your Tile Roof Is Too Old? Here Are Your Options
Understand the notice, document your roof's condition, and explore repair or replacement paths with a clear plan from ASP Superhome.
By Jonathan Rodriguez · Published October 24, 2026
If your insurer says your tile roof is too old, read the notice closely and answer it on time. A roof-age letter is usually a request for information or a notice of changed terms. It is not automatically a final decision. This guide explains what the letter likely means, what documents insurers ask for, and how a written tile roof assessment can help you choose a next step. It covers homeowners in Miami, Fort Lauderdale, West Palm Beach, Kendall, Boca Raton, Naples, and Fort Myers.
What a Roof-Age Letter From Your Insurer Usually Means
When an insurer says tile roof too old, the letter usually asks for information or changes your coverage terms. Treat it as a deadline, not a verdict.
Start by finding three things in the notice: the deadline, the reason given, and the action the insurer wants. Timelines can vary depending on the kind of request involved, so it is best to reply to any such request promptly.
Ask the insurer to name the roof-related reason in writing. A vague note about “roof condition” is hard to answer. A specific reason tells you what to repair, document, or replace. Common responses include a renewal condition, a request for an updated inspection, or a notice of changed terms. Each one calls for a different reply.
If your insurer has flagged your tile roof, we can look at its condition with you and lay out the repair or replacement steps that fit your home. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Old Is Too Old for Homeowners Insurance on a Tile Roof?
There is no single roof age that fits every insurer. The insurer’s written criteria are your starting point.
The Florida Office of Insurance Regulation explains that homeowners policies and eligibility can differ by insurer. It does not set a specific roof-age limit. Florida Office of Insurance Regulation
Citizens Property Insurance Corporation shows what a detailed review can look like. Its inspection page describes age thresholds for tile roofs and documentation of remaining useful life. It also describes proof of replacement when less than five years of useful life remains. Citizens Property Insurance inspections That is one insurer’s approach, not a rule for every company.
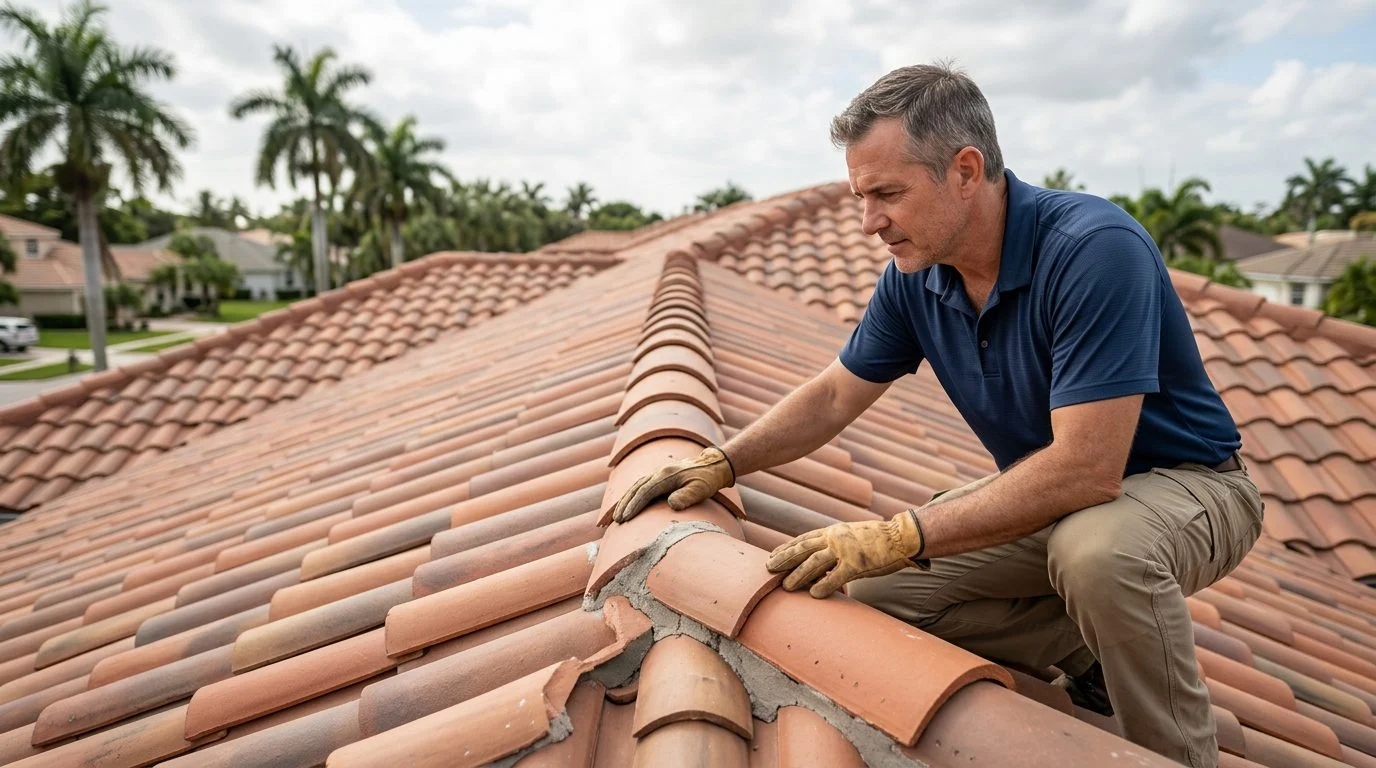
Age alone doesn’t describe condition. Tile roofs are judged on the tiles, underlayment, flashing, and fasteners, as well as the install date. A well-kept roof and a neglected roof of the same age can be assessed very differently. Whether your roof is treated as old depends on the facts of your roof and your policy.
What Documentation Insurers Typically Ask For
Insurers usually want proof of when the roof went on and what shape it’s in today. Gather these items before you reply:
- Install date: contractor invoices, permits, or closing documents that show the original roof.
- Current photos: every roof slope, ridge cap, valley, and roof penetration.
- Prior reports: inspections, repairs, and any tile replacement or mortar and adhesive work.
- Wind mitigation inspection: if one exists, it documents roof features tied to windstorm risk.
Keep every record dated and organized. Then you can send one packet instead of many scattered emails. Keep copies of everything you send.
Your Options When an Insurer Flags a Tile Roof
You can document the roof, repair identified problems, replace the roof or a section, or upgrade the roofing system. The right choice follows from what a professional assessment finds.
Start with a written assessment so the insurer receives facts, not guesses. Repairs fit cracked or slipped tiles, damaged flashing, or failing sealant. Keep invoices and photos of every repair. Replacement fits when the roof is near the end of its service life.
If you replace only part of the roof, Florida’s building rules may cover just that portion.
Code upgrades raise a coverage question. Your policy’s wording decides what it pays.
Reply in writing before the stated deadline. Include your documents and the work you plan to do.
Repair or Replacement: How to Decide What Fits Your Roof
A repair usually fits when the deck and underlayment are sound and the damage is limited to a few areas. Replacement becomes the stronger option when tile failure is widespread, the deck is damaged, or leaks keep coming back.
Attachment method matters on tile. The Tile Roofing Industry Alliance publishes installation guides covering proper tile-roof practices, code requirements, and high-wind applications in Florida. Tile Roofing Industry Alliance installation guides Ask which mortar or adhesive method your contractor plans to use, and why.
Structural capacity matters too. The National Roofing Contractors Association notes that clay and concrete tile are durable and used in Florida. It also says load capacity must be verified when tile replaces another roof covering. NRCA roofing materials guidance
Get the scope in writing. Ask for an itemized written estimate before any repair work begins. Before you sign a roof repair or replacement contract tied to an insurance claim, check your coverage with your insurance company.
Why a Written Tile Roof Assessment Helps With the Insurer
A written assessment gives you facts to send the insurer. It replaces a general claim that the roof is fine.
A useful assessment records the age indicators, the tile condition, the underlayment and flashing observations, and the recommended work in order. That gives the insurer a specific document to review. It also gives you a clear plan.
Roof features that affect windstorm risk are the ones a wind mitigation inspection records. Florida insurers must notify policyholders about available windstorm mitigation discounts at issuance and at each renewal. Discount eligibility generally depends on the wind-resistant construction features documented in a windstorm mitigation inspection. Florida Department of Financial Services
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Planning Solar or Batteries Alongside a Tile Roof Decision
Adding solar panels to a tile roof usually means removing and reinstalling tiles. Check the roof’s condition before the panels go on. Tile work can expose problems you would otherwise miss.
Solar and battery projects also change the records an insurer may see. Plan the roof repair or replacement first, or on the same schedule. Keep the permit, invoice, and photos from each step.
Link the decision to the roof’s remaining service life, not to the insurer letter alone. A roof with many good years left is a different decision from one near the end of its life. ASP handles solar panels and solar battery backup, so roof and solar work can be planned together.
Talk Through Your Insurer Letter With ASP
ASP can review your tile roof and explain the repair, replacement, or documentation steps that fit your situation. Bring the insurer notice, its deadline, and any roof records you already have. Your first consultation with ASP is free, confidential, and carries no obligation to continue. Use it to ask about your roof before you decide anything.
If your insurer’s letter is due back soon, reach out through the ASP contact page. Ask for a written tile roof assessment you can send with your response.
Frequently asked questions
What do I do if my insurer says my tile roof is too old?
Read the notice for its deadline and stated reason. Then reply in writing with your roof records before that deadline.
Does insurance pay for code upgrades on a tile roof?
Whether a claim pays for code-required upgrades depends on the policy’s law and ordinance coverage and how that coverage is worded.
How long do I have to report roof damage to my insurer?
How ASP Superhome Can Help
Roof Condition Review
We look at your tile roof's age, condition, and any visible wear so you have a clear picture of where it stands.
Repair or Replacement Options
We outline targeted tile roof repairs and full roof replacement options, so you can compare what fits your home and budget.
Documentation for Your Records
We can help you gather the photos, notes, and written estimate details that are useful when you respond to an insurer.
Confidential First Consultation
Your first consultation is free, confidential, and comes with no obligation to continue.
Don't Set the Notice Aside
An insurer's notice about your roof's age often includes a deadline and a stated reason. Read it right away, note every date it lists, and start gathering your roof information before you respond.
Steps to Take Now
1. Read the Notice Closely
Identify the stated reason, any dates listed, and what the insurer is asking you to provide.
2. Collect Your Roof Records
Gather installation receipts, prior permits, past repair invoices, and any inspection reports you have.
3. Get a Current Condition Assessment
A written inspection and estimate from ASP Superhome shows the roof's present condition and recommended next steps.
4. Respond in Writing
Send your documentation and a clear written reply to the insurer, and keep copies of everything you send.


