


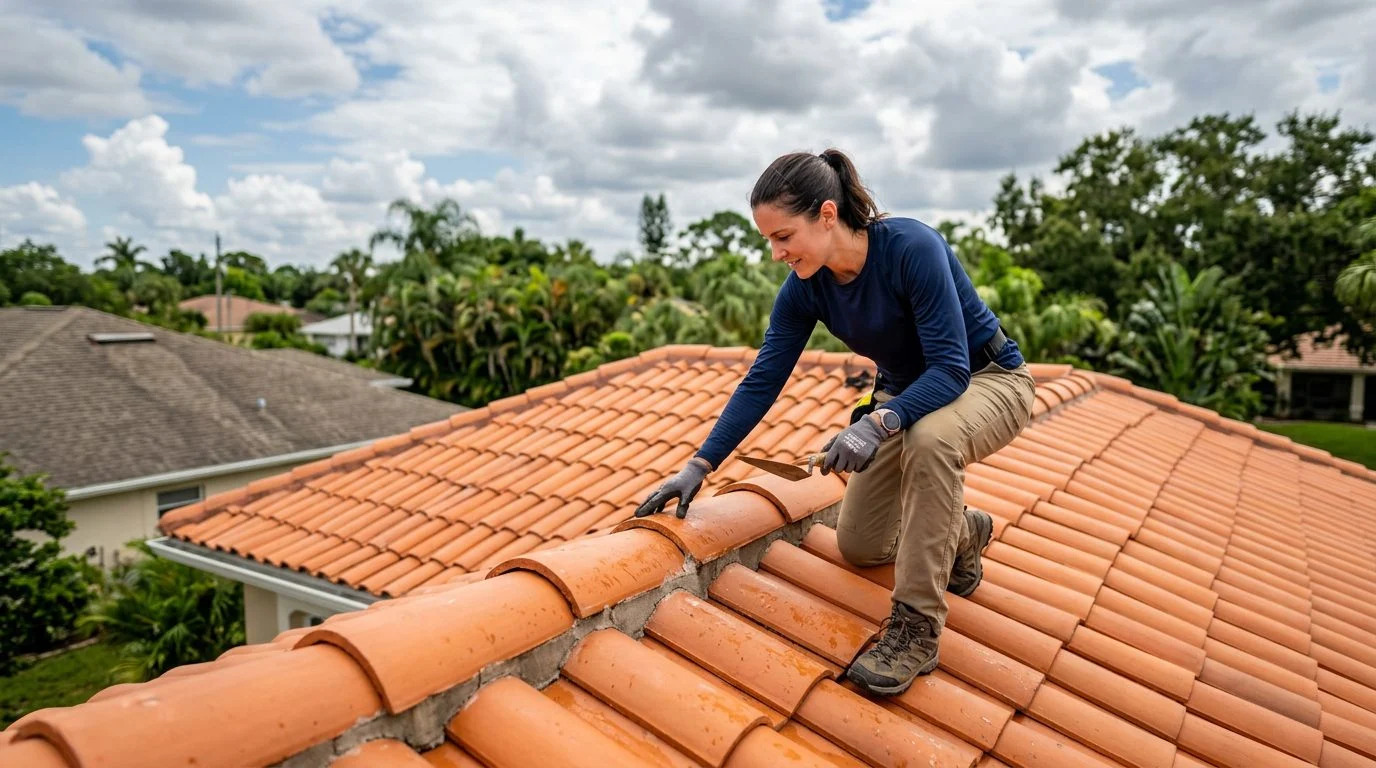
Tile Roofing | South Florida
Could a New Tile Roof Lower Your Florida Insurance?
Learn how a new roof, its materials and windstorm-resistant features may affect your premium, and how ASP Superhome can help you plan your next step.
By Jonathan Rodriguez · Published October 20, 2026
The Short Answer: A New Tile Roof Can Help, but Not Automatically
Will a new tile roof lower my insurance in Florida? It can help, but it won’t lower every policy by the same amount. The effect depends on your insurer, your policy, and the condition of your home.
Roof age is one factor. The roof’s wind-resistant features are another. Your home’s construction, location, and claims history also count. Think of the new roof as a reason to review your rating, not a guaranteed discount.
Florida law gives this review a legal basis. Under Fla. Stat. § 627.0629(1), the fixtures or construction techniques must include, but are not limited to, those that enhance roof strength and roof covering performance.
If your renewal premium went up or your tile roof is getting old, our team can talk through your options with you. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Florida Insurers Look at Roof Age and Roof Covering
Insurers look at how old your roof is and what it’s made of. Many insurers consider roof age when they set or renew a premium. An older roof can carry a higher rate, so the age of the covering matters.
Roof covering type matters too. Tile, metal, and shingle roofs may be rated differently in underwriting. Ask your insurer how it classifies your roof.
A replacement roof often changes the age figure your insurer uses. That is why homeowners ask about timing. If your roof is nearing the end of its life, replacement may be needed for condition reasons first. Insurance is one benefit to review, not the only reason to act.
Ask your insurer two questions. How does it record the installation date? What proof does it need? Common proof includes a permit, a signed contract, an invoice, and a completion record.
Wind Mitigation Credits and Why the Inspection Matters
Wind mitigation credits depend on what your home has and how well it’s documented. Florida rate filings for residential property insurance must include actuarially reasonable discounts, credits, or other rate differentials, or appropriate reductions in deductibles, for properties where windstorm mitigation fixtures or construction techniques shown to reduce windstorm loss have been installed or implemented. The Florida Department of Financial Services describes the wind-mitigation inspection as the basis for sending an inspection form to an insurer to find applicable credits.
Insurers must accept certain forms. Fla. Stat. § 627.711 requires a uniform mitigation verification form signed by an authorized inspector. That includes a licensed home inspector with at least 3 hours of approved hurricane mitigation training and a passed proficiency exam. A professional architect licensed under s. 481.213 is also among the listed qualifying professionals (§ 627.711(2)).
Insurers must post the hurricane mitigation discounts on their websites (§ 627.0629(1)). Insurers subject to this section must provide information on their websites describing the hurricane mitigation discounts available to policyholders. Your renewal notice is a good time to ask which credits apply to your roof and home.
How Tile Roof Structure and Code Rules Factor In
Building code rules shape what a replacement roof must include. Insurers look at the whole roof system. That includes the deck, the fasteners, the underlayment, and how the tile is secured.
For some homes, the code requires more than the tile. Fla. Stat. § 553.844 says that for site-built, single-family residential structures, a roof replacement on a building in the wind-borne debris region must incorporate the techniques in subparagraph (2)(b)3. when the building meets the statute’s threshold: an insured value of $300,000 or more or, if the building is uninsured or lacks documentation of insured value, a just valuation for the structure for ad valorem taxation of $300,000 or more. For existing buildings not otherwise required to comply with the Florida Building Code for new construction, Fla. Stat. § 553.844 says roof-to-wall connections are not required unless evaluation and installation at gable ends or all corners can be completed for 15 percent of the cost of roof replacement.
Permits matter too. Roof coverings play an important role in how a home performs during strong winds.
Common Homeowner Situations and What to Document
If your premium just went up, read your renewal notice closely.
If storm damage is involved, timing matters. Fla. Stat. § 627.70132 says a claim is barred unless notice was given within 1 year after the date of loss. A supplemental claim is barred unless notice was given within 18 months.
Roof deductibles can affect payment. Fla. Stat. § 627.7011 says an insurer may limit the roof payment to actual cash value until it receives reasonable proof you paid the roof deductible.
Keep these records together: photos, the signed contract, the permit, the final inspection, the invoice, and your declarations page.
Talk With Our Team About Your Roof and Premium
A tile roof decision is easier with the facts in hand. Florida law sets the framework, but your insurer and your roof’s condition shape the result. Our team can review your roof’s age, covering, and inspection status with you.
Does a new roof lower homeowners insurance in Florida?
A new roof can help, but the savings depend on your insurer and policy. Fla. Stat. § 627.0629(9) says that for residential property, insurers may file a personal lines rating plan that provides justified premium discounts, credits, or other rate differentials based on windstorm mitigation construction standards developed by an independent, nonprofit scientific research organization, if such standards meet the requirements of that statute.
How long is a wind mitigation inspection valid?
The Financial Services Commission sets guidance on how long inspection results remain valid.
Who can sign a wind mitigation form?
A licensed home inspector who has completed at least 3 hours of hurricane mitigation training and a proficiency exam can sign it, but must inspect the home personally, not through employees or other persons.
If your premium rose or your tile roof is aging, reach out to ASP Superhome. Our first consultation is free, confidential, and comes with no obligation to continue. Contact us at aspsuperhome.com/contact to talk through your roof and your renewal.
How ASP Superhome Can Help
Tile roofing
Our team focuses on tile roofing and roof replacement for South Florida homes, with attention to the materials and details that matter for wind performance.
Documentation for your insurer
We can help you understand what roof details your insurance provider may ask for when reviewing your policy.
Whole-home planning
Impact windows, impact doors, metal roofing and solar options can be planned together with your roof project.
Honest, clear answers
Ask us your questions about your roof, your home and your options before you make any decisions.
Check With Your Insurer First
Every insurance company rates policies differently. Before you count on a premium change, ask your insurance provider which roof details and documents it considers when reviewing your policy.
Questions to Ask Before Your Roof Project
What is the age and condition of my roof?
Roof age and condition are often part of an insurance review. Knowing where your roof stands helps you plan realistically.
What materials and installation records do I have?
Keep permits, product information and installation details together so they are easy to share with your insurer.
Are my windows and doors impact rated?
Windstorm protection for openings can be part of the same conversation as your roof, so review them together.
Would solar or battery backup fit my plan?
Solar panels and battery backup can be planned alongside a roof replacement to keep your project organized.


