


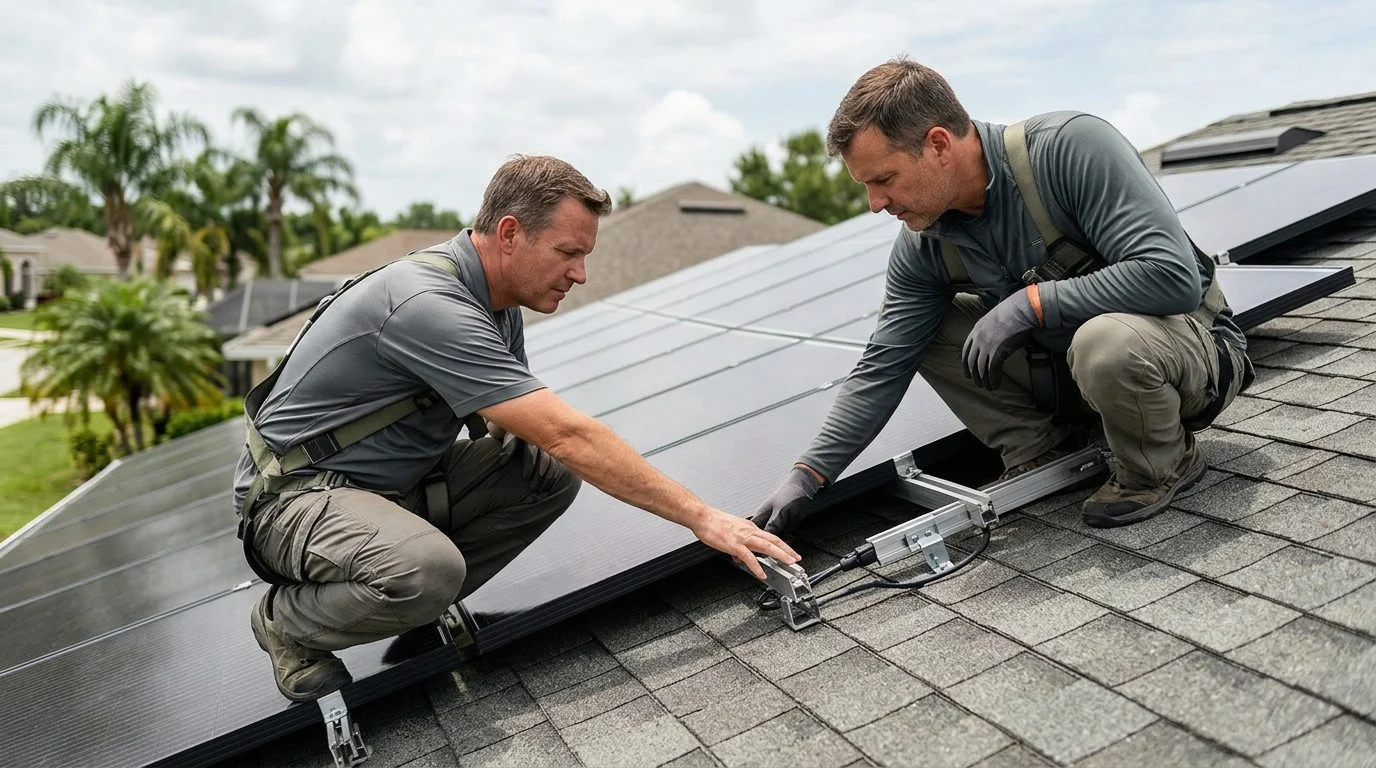
Solar Battery Backup | South Florida
Does a Solar Battery Lower Your Homeowners Insurance?
It can, but it doesn't always. Here's what to ask your insurer about your battery, and how ASP Superhome can help you plan your solar battery backup.
Start with a Free First Consultation
Free
First consultation
Confidential
Your details stay private
No obligation
No commitment to continue
By Jonathan Rodriguez · Published October 30, 2026
A solar battery can change your policy, but whether your premium goes down, goes up, or stays the same depends on your insurer and your policy. This guide explains what drives that answer.
Short Answer: Can a Home Battery Change Your Homeowners Policy?
A home battery can change how your policy is written and priced. The result depends on the insurer’s own rating rules, the policy form, and any endorsements attached to it. Two homes with the same battery can end up with different premiums.
The battery is one input among several. Florida’s regulator explains that homeowners coverage depends on the policy form and on which perils are covered or excluded (Florida homeowners insurance overview). A battery matters only as far as your policy treats it.
If you want the broader picture of battery backup, start with our solar battery backup guide for South Florida.
If a battery or an insurance notice has you unsure where you stand, our team is ready to talk through your situation with you. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Do I Need to Add a Solar Battery to My Homeowners Insurance?
Usually, the battery belongs on your policy. A battery installed on the property is typically treated as part of the dwelling, which is the structure your policy insures. Ask your insurer how the system is recorded, and check that the record matches what was installed.
Dwelling coverage protects the house and the equipment attached to it. Personal property coverage protects your belongings, such as furniture, clothing, and electronics. A wall-mounted battery usually falls under dwelling coverage. Confirm that in writing with your insurer.
Equipment added after your policy started may need to be reported. Many homeowners assume it is covered automatically. Don’t wait for renewal to tell your insurer about a new system.
Start by pulling your declarations page, which lists your coverage limits and main policy terms. Then read every endorsement. Look for any exclusion that names solar or electrical equipment.
How Insurers Look at Solar Panels and Battery Systems
Insurers look at a battery in three main ways: what it costs to rebuild, how it is installed, and what paperwork supports it. Each one can change the result.
Start with cost. A battery adds to what the home costs to rebuild. If your dwelling limit was set before the install, that limit may not reflect the system.
Next is fire safety. The Florida Building Commission’s 2026 residential code analysis reports new language for openings into the home from battery spaces. Requirements for fire-rated doors depend on the building and local code, and our team can review what your project needs. The doors must be self-latching and self-closing. Insurers may ask whether an install meets current code.
Insurers may also ask for installation records, permits, and equipment specifications. Keep these together. They show what was installed and when.
Finally, each insurer’s underwriting guidelines decide how solar and battery equipment is classified. The same system can be treated differently by different insurers.
Why a Policy Only Matters on the Worst Day
Coverage gaps usually show up during a claim, not on a routine bill. A policy can look fine on paper until a storm, fire, or electrical fault tests it. That’s when you learn whether the battery was covered as written.
Common gaps include equipment not listed on the policy, coverage limits set before the install, and endorsement exclusions nobody noticed. Each one can leave part of a loss on you.
Timing matters too. Florida law bars a property claim, other than a supplemental claim, unless notice was given within 1 year after the date of loss. A supplemental claim is barred unless notice was given within 18 months (Florida Statutes § 627.70132). For hurricanes, the date of loss is the date the storm made landfall.
After any major equipment install, pull your policy. Check the dwelling limit, the endorsements, and whether your insurer has the updated equipment details. Keep a dated note of what you found.
Cancellation and Non-Renewal Notices Tied to Solar Equipment
Florida news reports have described homeowners with solar panels receiving cancellation notices. Read any notice like this right away, because its dates matter.
Read the stated reason closely. Note the effective date, any response deadline, and the date you received the notice. A short window leaves little time to act.
If you want your insurer to review the notice, gather what supports your position. Useful records include permits, the installation contract, equipment specifications, and photos of the system. Keep copies of everything you send.
Florida Storm Risk, Wind Load, and Permits
Homeowners in Miami-Dade and along the Gulf Coast often ask how wind affects rooftop and mounted equipment. Wind load is the force wind puts on a structure and anything fixed to it. A documented mounting system gives you a record to show.
Permits are part of that record. Florida law requires a local enforcement agency to post and update the status of every received permit application until the permit is issued. It must also allow electronic submission (Florida Statutes § 553.79).
Keep your permit numbers and inspection records in one place. A permit shows the work went through review. Engineering documents, if your installer provided them, belong in the same file.
Roof work matters too. Florida law says a roof replacement on a site-built, single-family residential structure must incorporate certain techniques, including secondary water barriers and roof-decking attachment (Florida Statutes § 553.844). File roof records with your solar records.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Questions to Bring to Your Insurer and What to Gather First
Before you call your insurer, gather these in one folder: the installation contract, permit numbers, panel and battery make and model, system size in kW, battery capacity, installation date, and dated photos.
Then ask specific questions. How is the battery classified on my policy? Does it change my dwelling coverage limit? Is an endorsement needed? How was my renewal premium calculated?
Florida law requires at least 45 days’ advance written notice of the renewal premium for residential property policies (Florida Statutes § 627.4133). Use that window to review the numbers.
Ask your insurer whether a battery affects any discount it offers.
Frequently Asked Questions
Does a solar battery lower homeowners insurance in Florida?
It can, but it doesn’t always. The insurer’s rating rules and your policy form decide the result.
Do I need to add a solar battery to my homeowners policy?
Ask your insurer how the battery is recorded. Equipment added after your policy began may need to be reported.
Talk Through Your Situation With Our Team
If a renewal arrived with a question you didn’t expect, or a cancellation notice about solar equipment came in the mail, you may feel rushed. You may also be deciding whether a battery fits a home you’re responsible for, and you want the facts first.
Our first consultation is free, confidential, and carries no obligation to continue (consulta inicial gratuita, confidencial y sin compromiso).
If your battery or a notice has you unsure, our team can walk through your system, its paperwork, and the questions to raise with your insurer. Contact us here.
Steps to Take Before You Install
Tell your insurer about the battery
Let your insurance provider know a solar battery is part of your home plan so they can review it with you.
Ask how it will be recorded
Find out whether the battery is listed on your policy and how equipment added after your policy began is handled.
Review your policy form
Read the coverage details that apply to your home's systems so you understand how the battery is treated.
Keep your equipment records
Save the installation details and documentation for your battery and solar panels in one place.
How ASP Superhome Can Help
Plan your solar battery backup
Our team can walk you through battery options that fit your home and your energy needs.
Organized project details
We can help you document your system so it is easier to share with your insurer.
Honest answers, no pressure
Ask your questions in a confidential, no-obligation conversation before you decide anything.
Serving South Florida homeowners
We work with homeowners in Miami, Fort Lauderdale, West Palm Beach, Boca Raton, Naples, Fort Myers, and Kendall.
Don't Assume Your Premium Will Change
A solar battery may or may not affect your homeowners insurance. Confirm with your insurer how the battery will be recorded before you assume any change in your coverage or cost.


