


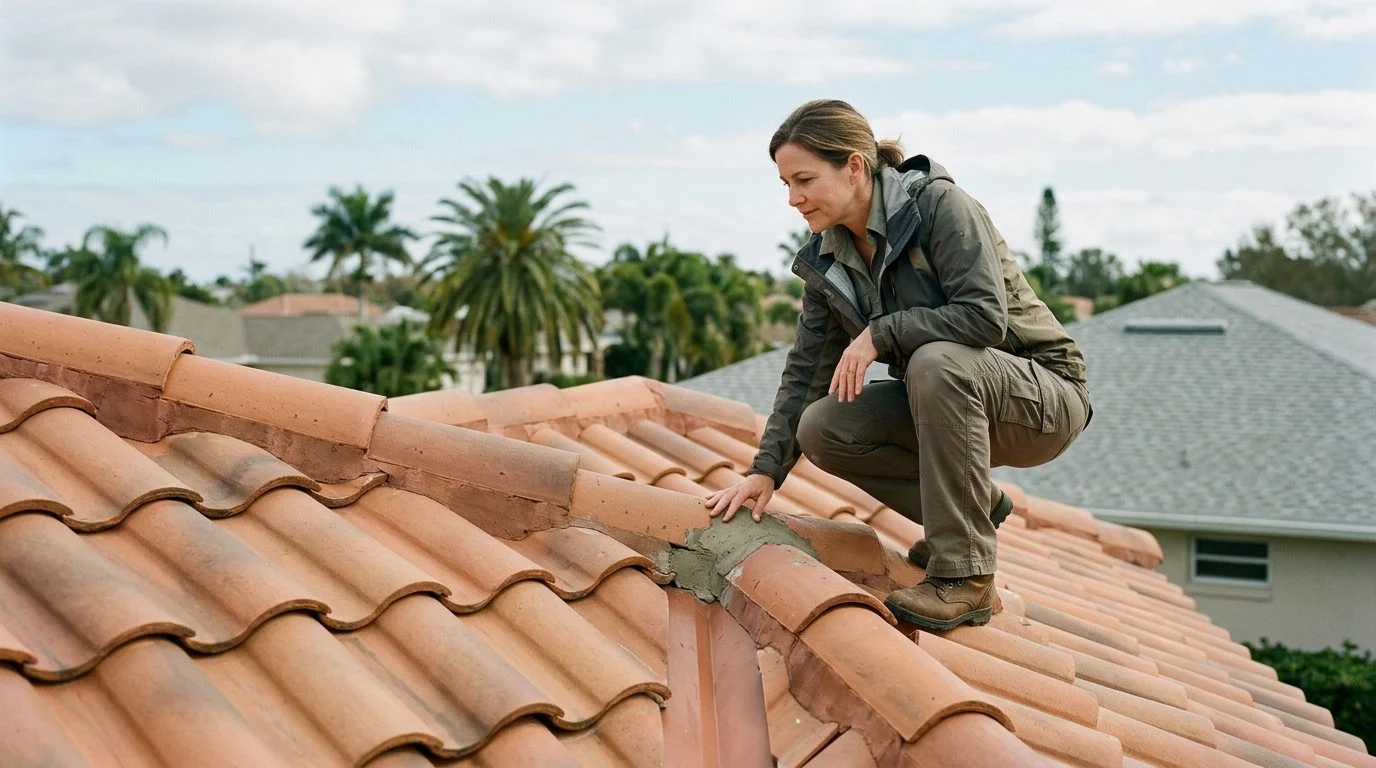
Tile Roofing & Roof Replacement | South Florida
Tile Roof Replacement in Florida: How Insurance Can Help Pay
Learn how homeowners insurance may apply to a tile roof replacement after storm damage, and what to document before you start.
By Jonathan Rodriguez · Published October 28, 2026
Short Answer: When Florida Homeowners Insurance Pays for a Roof Replacement
Florida homeowners insurance generally pays for roof damage caused by a sudden, covered event, such as windstorm, hail, or a fallen tree. It generally does not pay for normal wear, age, or lack of upkeep. The payout also depends on your policy’s valuation method, your deductible, and the roof’s condition.
A full replacement usually comes into play when repair isn’t practical or the damage covers much of the roof. A few cracked tiles often call for repair. Widespread breakage, tiles displaced by wind, or leaks that repairs can’t fix may point toward replacement.
This page walks through how insurers calculate a tile roof payout. For the broader picture, see our roof replacement guide.
If a storm has cracked your tile roof and the insurer's payout is unclear, our team can help you work out your next step. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What Actual Cash Value Means for a Tile Roof
Actual cash value (ACV) is replacement cost minus depreciation for age and condition. Think of it as what the roof was worth on the day of the loss.
Here’s a simple example. A newer roof is worth more than an older one. So the insurer subtracts a share of the cost, called depreciation, before it pays. The amount subtracted depends on the insurer’s method and your policy.
Tile roofs add a twist. Tile is durable, but the underlayment and decking beneath it wear out on their own schedule. An adjuster may value the tile, underlayment, and decking differently. Read your declarations page to see which valuation method applies to your policy. Then ask your insurer how it applies depreciation to each part of the roof.
What Replacement Cost Coverage Pays and How Holdbacks Work
Replacement cost value (RCV) is the cost to repair or replace the roof without subtracting depreciation. It is capped at your policy’s dwelling coverage limit.
Florida law sets a clear sequence. Under Fla. Stat. § 627.7011, for a dwelling insured on the basis of replacement costs, the insurer must first pay at least the actual cash value of the loss, minus your deductible. It must then pay the remaining amounts needed for the repairs as work is performed and expenses are incurred.
That gap between ACV and RCV is the holdback. You usually receive it as the work moves forward. Keep your contractor’s invoices and proof of payment, because they support each release.
The same statute allows an insurer, if a roof deductible under s. 627.701(10) is applied to the insured loss, to limit the roof portion of a claim to ACV until it gets reasonable proof you paid the roof deductible. Proof can include a canceled check, a money order receipt, a credit card statement, or a copy of a signed installment plan contract or other financing arrangement that requires full payment of the deductible over time.
Tile Roof Replacement Costs and What Drives the Price
The cost of a tile roof replacement is driven by the tile type, roof size and pitch, tear-off, underlayment, and any decking repairs. Labor and tear-off often make up a large share of the total, not just the tile.
Take a 2,000 square foot home with a typical pitch. The adjuster measures the roof area, counts the tile, and prices removal, underlayment, and labor. A steeper pitch takes more labor and safety gear, which raises the figure.
Tile type matters too. The NRCA roofing materials guidance covers clay and concrete tile and notes that structural load capacity should be verified when tile replaces another roof covering.
Code requirements add to the scope.
In Miami-Dade, the Miami-Dade roofing permits page lists the forms, checklists, e-permitting, and hurricane-mitigation documents for roofing applications.
Florida Windstorm Deductibles and Hurricane Wind Claims
Many Florida policies carry a separate windstorm or hurricane deductible. This deductible can be different from the deductible you use for other losses.
The deductible comes off before the insurer pays. A large wind deductible can leave a much smaller net payment than the repair estimate suggests.
For hurricanes and other weather events, the date of loss matters. Under Fla. Stat. § 627.70132, the date of loss is the date a hurricane made landfall, or the date a windstorm or other weather event is verified by the National Oceanic and Atmospheric Administration. That date starts the notice clock.
Cracked, Broken, or Sagging Tiles: Documenting Damage for a Claim
Good documentation starts with dated photos of the damage. Add a written account of the storm and any interior water damage.
Look for cracked or broken tiles, tiles shifted or missing after wind, leaks, and sagging in the decking or rafters. Each sign helps show what the storm did to the roof.
Keep receipts for temporary repairs, such as tarping. Your insurer may ask for them when reviewing the claim.
Timing is critical. Under Fla. Stat. § 627.70132, a claim is barred unless notice was given under the policy within 1 year after the date of loss. A supplemental claim for added damage from the same event is barred unless notice was given within 18 months.
Older roofs bring extra steps. The Citizens Property Insurance roof inspection page describes age thresholds and roof documentation for its underwriting.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Preparing for Your Tile Roof Replacement Claim Step by Step
Start with your declarations page. Note the valuation method, the dwelling limit, and the windstorm deductible. Then compare the adjuster’s estimate with what a code-compliant tile installation requires.
Ask whether the estimate includes underlayment, decking repairs, permits, and wind-uplift rated installation. Missing items can mean a gap between the estimate and the final bill.
Florida law protects you during the estimate stage. Under Fla. Stat. § 489.147, a contractor may not give you a repair agreement for an insurance claim without a good faith estimate of itemized, detailed costs. The contractor doesn’t violate this if the final cost differs because the insurer adjusted the claim.
A roof contract must also carry a bold notice of at least 14 points. It tells you to verify coverage with your insurer before you sign.
The general timeline runs from inspection to estimate, then permit, installation, and the holdback release. Permits matter here. Under Fla. Stat. § 553.79, it is unlawful to repair or alter a building in Florida without first obtaining a permit, unless otherwise provided by law. For Miami-Dade projects, see our Miami-Dade tile roof replacement guide.
Talk Through Your Roof Claim With Our Team
Our team can discuss tile roof repair and replacement with you during a free first consultation, which is confidential and carries no obligation to continue.
You can contact ASP Superhome for a free first consultation. It is confidential and comes with no obligation to continue.
Does homeowners insurance pay for a tile roof replacement in Florida?
It can, when the damage comes from a sudden, covered event like windstorm or hail. Normal wear and age are generally not covered.
How long do I have to report a roof claim in Florida?
Under Florida law, a claim generally must be reported within 1 year after the date of loss. A supplemental claim has an 18-month window.
Why does my insurer pay only part of my tile roof replacement upfront?
The remaining amounts are paid as the work is done.
Does a tile roof replacement in Florida need a permit?
Florida law generally requires a permit before a building is repaired or altered. Confirm the permit before work starts.
Why Homeowners Start with ASP Superhome
Tile Roofing Focus
Our team focuses on tile roofing and full roof replacement, so your project is planned around the roof you have.
Clear Documentation
We help you record the condition of your roof so you have a clear picture of the work involved.
Straightforward Communication
We explain your options in plain language, from the scope of work to what to expect at each stage.
Built for South Florida
We work with homeowners in Miami, Fort Lauderdale, West Palm Beach, Kendall, Boca Raton, Naples and Fort Myers.
Before Any Repairs Begin
Take clear photos and video of the damage, keep any storm-related notes, and save your insurance policy documents. Good records make it easier to review your situation with your insurer.
Common Questions About Tile Roof Replacement
Does insurance always cover a new tile roof?
Coverage depends on your specific policy and the cause of the damage. Sudden events such as windstorms and hail are treated differently from gradual wear over time.
What is the difference between repair and replacement?
A repair fixes isolated damage, while a replacement may be needed when tiles, underlayment or the structure are compromised across a large area. A roof assessment helps clarify which applies.
Can I upgrade my roof while replacing it?
Many homeowners consider impact-resistant materials or other improvements during replacement. Discuss these options with our team to understand how they fit your home and budget.
What should I expect from the process?
Expect an inspection, a review of the roof's condition, a written scope of work, and clear guidance on scheduling. Your free consultation is the best place to start those conversations.


