


Metal Roofing | South Florida
Could Your Metal Roof Lower Your Florida Insurance Bill?
Learn how a metal roof may support a wind mitigation credit, what the form covers, and how to plan your next step with ASP Superhome.
By Jonathan Rodriguez · Published October 28, 2026
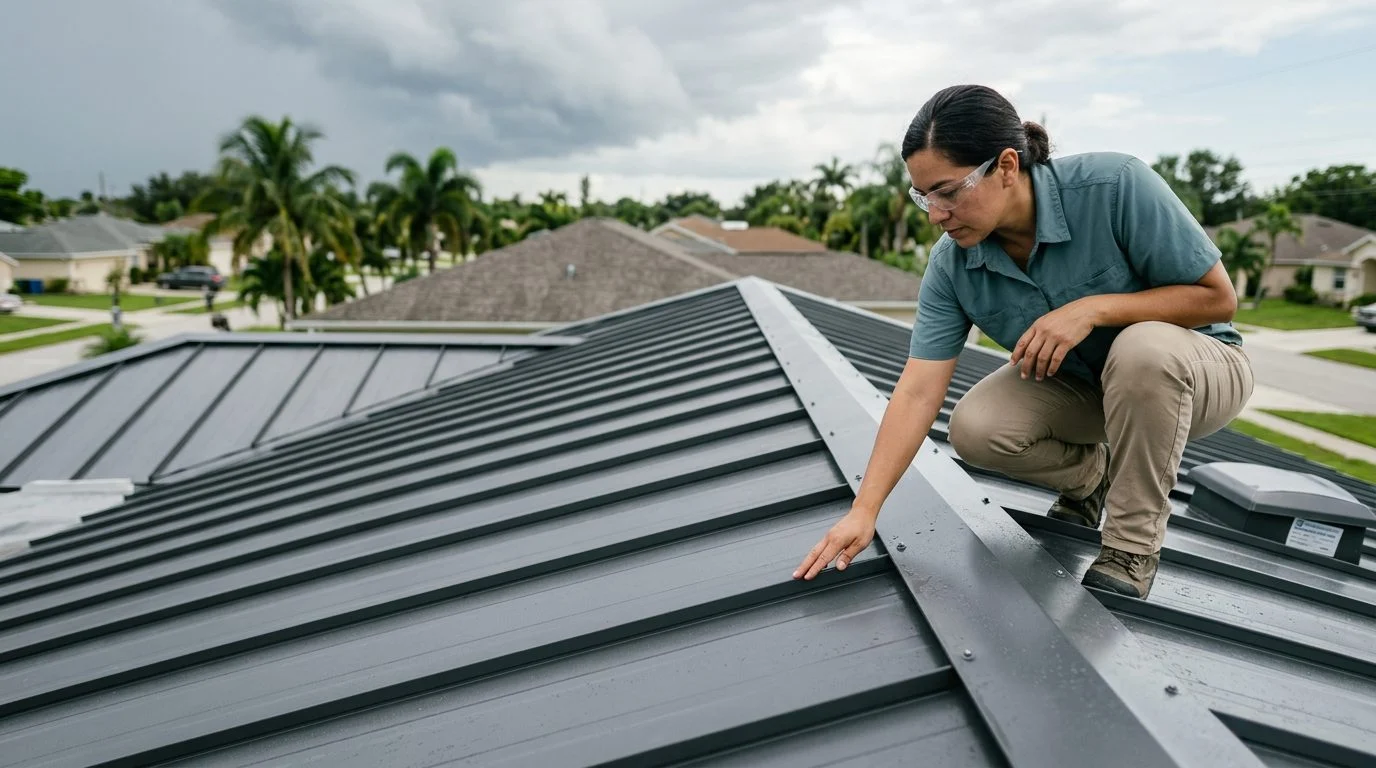
Will a metal roof lower homeowners insurance Florida premiums? It can help, but the credit isn’t automatic. A metal roof can support a wind mitigation credit. Your insurance carrier makes the final call, and the completed inspection form is the key record.
A metal roof can earn wind mitigation credits, but not automatically
A metal roof can earn wind mitigation credits once your insurer accepts a completed inspection form. Many homeowners assume a new roof lowers the bill on its own. That skips the form and the carrier’s rules. The Florida Office of Insurance Regulation describes premium discounts for hurricane loss mitigation. Under Fla. Stat. § 627.711, insurers must notify applicants or policyholders of personal lines residential property insurance policies of the availability of windstorm mitigation discounts when a policy is issued and at each renewal. The credit is a premium discount, so it reduces the premium the carrier charges. Roof covering is only one feature. State roof rules also cover items such as roof-to-wall connections (Fla. Stat. § 553.844). So a metal roof helps while the other features still count.
If you're weighing a metal roof replacement and want to know how it could affect your premium, reach out for a free estimate that includes the paperwork your inspection needs. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What a wind mitigation inspection looks at
A wind mitigation inspection records a home’s wind-resistance features on a standard state form. The Financial Services Commission develops that form, and all insurers use it when a policyholder submits it for wind discounts. The form is designated OIR-B1-1802 (Fla. Admin. Code R. 69O-170.0155). Fla. Admin. Fla. Admin. Code R. 69O-170.0155 adopts the OIR-B1-1802 “Uniform Mitigation Verification Inspection Form” and requires insurers to submit to the Office of Insurance Regulation, through its web portal, the information in any such form they receive that relates to the policy, within 60 days from the effective date of a rate change to the policy or 60 days from the effective date of the policy, whichever occurs later. Insurers may not submit the insured’s name, telephone number(s) or email, or any policy they did not issue. The form’s details must match the finished roof. A mismatch can slow down the credit.
How a metal roof covering shows up at inspection
The roof covering is part of what the form records, so the product and its installation both matter. Florida law says a roofing product may not be sold or marketed as hurricane protection unless it is approved under the state’s product approval system (Fla. Stat. § 553.842). Roofing, windows and exterior doors all fall under that approval system. Keep the product name, model and approval paperwork in your roof file. Storm performance is a separate question. The IBHS Hurricane Ian roof findings say metal roof systems held up well in winds below 130 mph in Southwest Florida. That is a finding about storm performance, not an insurance rule. Metal roofing and tile roofing both fall under these product rules, so bring the product details for either roof.
Roof deck and roof-to-wall connections come next
Roof-to-wall connections tie the roof framing to the walls, and Florida law sets a cost test for adding them. The statute also adds a limit. For existing buildings that are not otherwise required to comply with the Florida Building Code for new construction, roof-to-wall connections aren’t required unless the work at gable ends or all corners can be completed for 15 percent of the cost of roof replacement (Fla. Stat. § 553.844). The roof deck is the sheathing under the covering. Ask your contractor to list the deck and fastener work on the invoice, so those details are on paper.
Why your carrier and the form decide the discount
Your insurance carrier applies the discount, so its rules control the final amount. Florida’s windstorm discount rule ties insurer discounts to specific Office of Insurance Regulation forms. It also bars changes unless detailed alternate studies support them (Fla. Admin. Code R. 69O-170.017). The carrier’s table should match those forms. Two homeowners with similar metal roofs can still see different credits. Each carrier’s policy terms decide how the credit appears on your bill, so ask your carrier which steps it requires.
Documents that help the credit get applied
Keep your roof paperwork together and send it with the completed form. Save product approval information, permit records and an itemized contractor invoice. Keep the originals and a copy of every page you send. Under Fla. Stat. § 627.711, knowingly providing a false or fraudulent mitigation verification form to get a premium discount you are not entitled to is a first-degree misdemeanor.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Planning a metal roof replacement in South Florida
Timing matters because roof discounts are often limited to newer roofs. Hurricane season is a common reason homeowners plan early, and planning ahead gives you time to gather paperwork. Homeowners in Miami, Kendall, Fort Lauderdale, Boca Raton, West Palm Beach, Naples and Fort Myers face the same state rules on these credits. Metal roofing and tile roofing are both part of our roof replacement work. The right choice fits the home’s structure and your goals. Before you choose, check your renewal date and your roof’s installation date together. That shows which discount question to ask first.
Request a free estimate for your metal roof
The next step is a free estimate that covers your roof details and product paperwork. Ask that product approval information, installation details and permit steps be part of the quote, so you have them for your inspector and carrier. Bring your current policy, your roof’s installation date and any past inspection form. Your first consultation is free, confidential, and carries no obligation to continue. If you’re weighing a metal roof replacement and want to know how it could affect your premium, reach out for a free estimate that includes the paperwork your inspection needs.
Frequently asked questions
Will a metal roof lower homeowners insurance Florida rates?
A metal roof can support a wind mitigation credit. Your insurance carrier makes the final decision on the discount, based on the completed form.
Who can sign a wind mitigation form in Florida?
A licensed home inspector under s. 468.8314 who has completed at least 3 hours of hurricane mitigation training approved by the Construction Industry Licensing Board and completed a proficiency exam can sign it (Fla. Stat. § 627.711). A licensed general, building, or residential contractor can sign it too, as can a certified building code inspector, a licensed architect, and others the statute lists (Fla. Stat. § 627.711).
Does roof age affect the discount?
Our team can review your roof’s details during a free initial consultation, which is confidential and without obligation.
What to Know About Metal Roofs and Insurance
Wind-Resistant Roofing
Metal roofing is a durable option for South Florida homes, and it is one of the roof features that can be relevant to a wind mitigation review.
The Wind Mitigation Form
A completed wind mitigation form documents features of your home that may affect your homeowners insurance premium.
Your Insurer Decides
Your insurance carrier makes the final decision on any discount, based on the completed form and its own underwriting.
Plan Ahead With Our Team
Our team can talk through your roof, your timeline, and your options before you make any decisions.
Don't Assume a Discount Applies
A metal roof may support a credit, but it does not guarantee one. Confirm with your insurance carrier before you count on any savings.
How to Prepare
Gather Your Roof Details
Note your roof's age, material, and any recent repairs or replacements so you have the basics ready.
Review Your Policy
Look at your current homeowners policy and note your renewal date and any wind-related deductibles.
Ask About the Form
Contact your insurance carrier to learn what wind mitigation information it accepts and how it processes the form.
Talk With Our Team
Share your goals with ASP Superhome to discuss metal roofing options for your home in Miami, Fort Lauderdale, West Palm Beach, or nearby areas.


