


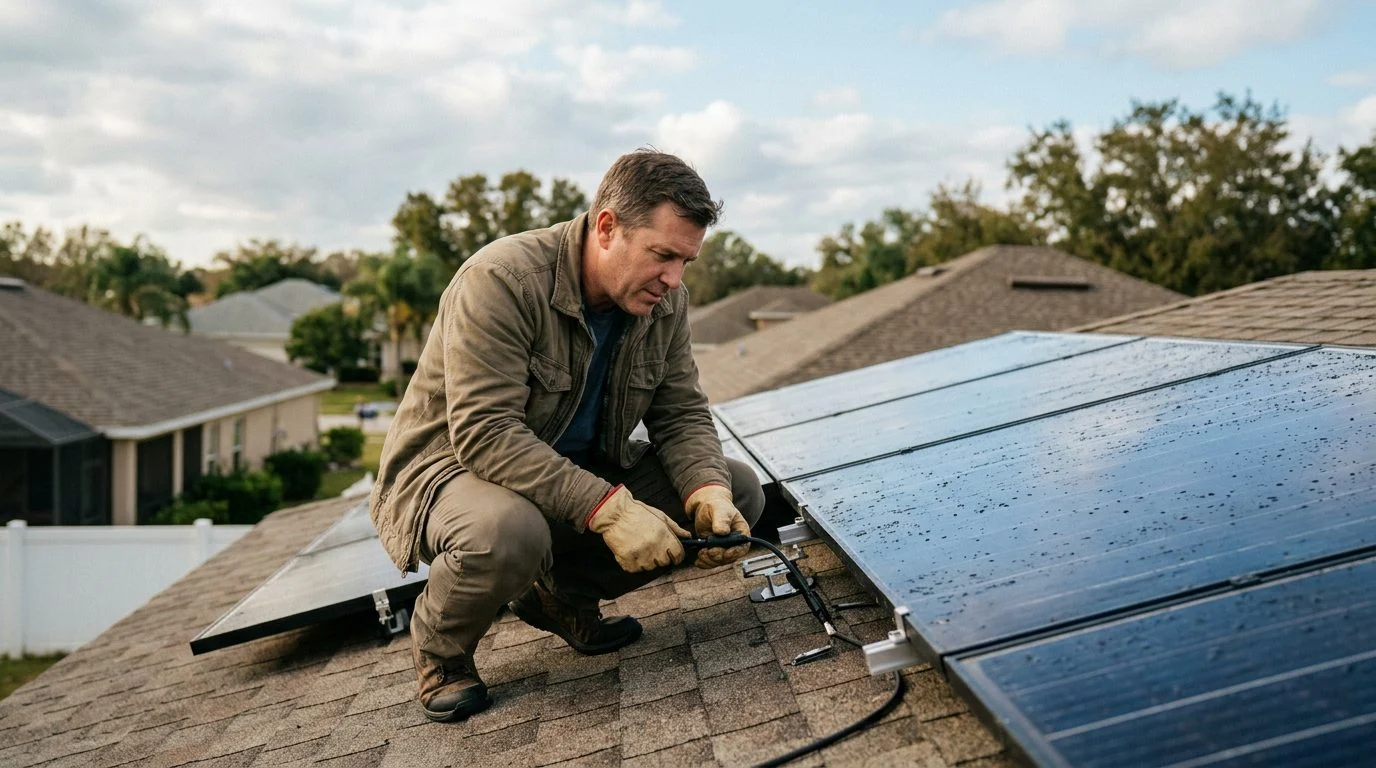
Solar Battery Backup | South Florida
Thinking About a Solar Battery? Start With Your Home Insurance Questions
Learn how solar battery backup can affect your home insurance conversation, and what paperwork helps when you ask about a possible discount. Begin with a free, confidential first consultation with no obligation to continue.
By Jonathan Rodriguez · Published November 7, 2026
A solar battery may be considered in a Florida homeowners insurance review, but the insurer decides whether any solar battery homeowners insurance discount applies. No battery guarantees a lower premium. Each insurer sets its own rules.
This page explains how the review usually works, what to gather, and which questions to ask before you count on any savings.
Short Answer: A Solar Battery May Be Considered, but the Insurer Decides
A solar battery may be considered, but it does not earn a discount on its own. Each insurer’s rate filing must include these discounts, while the Office of Insurance Regulation determines the discounts that reflect full actuarial value, which insurers may use in their filings.
Florida law requires insurers’ residential rate filings to include actuarially reasonable windstorm discounts for properties where qualifying fixtures or construction techniques have been installed or implemented. Under Fla. Stat. § 627.0629, a rate filing must include actuarially reasonable discounts for features shown to reduce windstorm loss. The named examples focus on the structure: wind uplift prevention, roof strength, roof covering performance, roof-to-wall strength, wall-to-floor-to-foundation strength, opening protection, and window, door, and skylight strength.
Battery storage is not one of the named examples. The list is not limited to those examples, though, so an insurer may review other features. Your insurer’s own filing decides what it credits.
That means adding solar or a battery does not automatically lower your premium. Read your renewal notice, then call the company with specific questions.
If a renewal notice has you wondering what your solar battery means for your premium, you don't have to work it out alone. Our team can review the whole home with you. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Home Insurers Typically View Solar Panels and Battery Storage
An insurer may look at the whole home, not just the equipment you add. Roof condition, electrical systems, windows, and doors can all shape the review.
Roof details matter. The Florida Department of Financial Services says homeowners roof discounts vary by insurer. They depend on roof age, condition, and type.
So how does solar affect home insurance? Mostly through the home’s overall profile and the policy terms. Adding equipment can change what the insurer needs to know about the property.
Replacement cost coverage is also worth checking. Policies differ on whether they pay for code-required upgrades during a repair, so the policy’s terms determine what is covered.
The U.S. Department of Energy’s Solar Energy Technologies Office publishes guidance on energy storage and battery backup. That guidance can help you describe what your system does.
A federal tax credit is a separate question. Federal tax credits for home energy equipment are subject to conditions that can change, so review the current requirements on the Internal Revenue Service website. That credit does not change your insurance premium.
Florida’s Insurance Regulatory Backdrop
The Florida Office of Insurance Regulation oversees how windstorm discounts are explained to homeowners. That is why insurers publish their own discount information.
Under Fla. Stat. § 627.711, an insurer must clearly notify the applicant or policyholder of any personal lines residential property insurance policy of the availability and range of available discounts when the policy is issued and at each renewal. The notice uses a form prescribed by the Office of Insurance Regulation. It must describe generally what you may do to reduce your windstorm premium.
The Office of Insurance Regulation explains that Florida homeowners use an official mitigation inspection form. They submit it to an insurance agent to seek hurricane-wind discounts.
Since October 1, 2023, insurers must also describe their hurricane mitigation discounts on their websites, and that information must be accessible on, or through a hyperlink located on, the home page or the primary page for property insurance policyholders, under § 627.0629.
Rules and filings can change. Confirm current terms with your insurer before you assume a credit.
Documentation to Gather Before You Ask About a Discount
Gather your paperwork before you call. A clear paper trail helps an underwriter review the system and cuts down on back-and-forth.
Start with these items:
- The installation contract or invoice.
- Equipment specifications for the battery and inverter.
- Permit and inspection records.
- The installation date.
Florida law requires a permit before altering a building. Under Fla. Stat. § 553.79, unless otherwise provided by law, it is unlawful to alter or repair a building without first obtaining a permit. Keep the permit and inspection sign-off with your other records.
Code terms also change. According to the Florida Building Commission analysis, the 9th Edition (2026) FBC, Residential retitles R328 from “Stationary Storage Battery Systems” (8th Edition, 2023) to “Energy Storage Systems” (9th Edition, 2026). It moved from “Stationary Storage Battery Systems” in the 2023 edition to “Energy Storage Systems” in the 2026 edition.
Describe the battery’s role, such as backup power during outages, the same way your installation documents do.
Questions to Ask Your Insurer About Solar and Battery Storage
Ask your insurer about its rule for solar and batteries, and where that rule is written. Then ask these questions:
- Does the company have a stated policy on solar panels or battery storage? Where is it described?
- Does the company need notice when new equipment is added? If so, how soon?
- Would the battery fall under the dwelling limit, and how is it treated at renewal?
- What information does the underwriter need to finish the review?
Ask whether any solar battery homeowners insurance discount applies, and under what conditions. Ask about wind mitigation inspections, too.
Under § 627.711, the Financial Services Commission develops a uniform mitigation verification inspection form. All insurers must use it when policyholders submit it to have wind discounts factored in. The commission also gives guidance on how long inspection results stay valid, so ask how long this company accepts them.
How Impact Windows, Impact Doors, and Roofing Fit Into the Review
Impact windows, impact doors, and roofing relate closely to the windstorm features in Florida’s discount statute. Section 627.711 covers the uniform mitigation verification form and does not list these features; the windstorm examples of roof covering performance, roof strength, opening protection, and window, door, and skylight strength are in § 627.0629.
These features may be reviewed alongside solar and storage as part of the whole-home profile. Whether any of them earns a credit depends on the insurer’s filing and on documentation of the work.
Roof type also matters, according to the Department of Financial Services guidance above. For roof-specific questions, read our tile roof FAQ. For how the battery system works, see our South Florida solar battery backup guide.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Planning an Installation: Timing, Roofing, and Local Permits
Answer the roof question before you install a battery. If a roof repair or replacement is part of the plan, it can change the scope of the work.
For an existing roof built, repaired, or replaced under the 2007 Florida Building Code or a later edition, if 25 percent or more of the roofing system or roof section is repaired, replaced, or recovered, only that repaired, replaced, or recovered portion must be constructed to the Florida Building Code in effect. Ask your roofer how this applies to your roof.
If roof work is linked to an insurance matter, your roofing agreement may include a notice advising you to contact your insurer and check what your insurance policy covers and what you would pay out of pocket before you agree to it. Read the notice carefully before you agree to it.
Miami-Dade County permits and inspections can add time. Timelines depend on the home and local requirements. For a rough sense of the schedule, see our Miami-Dade battery installation timing guide.
Take the Next Step With ASP Superhome
Frequently Asked Questions
No battery guarantees a lower premium.
Does solar affect home insurance?
It can change what the insurer reviews and what it needs to know about the home. Replacement cost terms may also matter.
What should I bring when I ask about a discount?
Bring the installation contract or invoice, equipment specifications, permit and inspection records, and the installation date.
Is a federal tax credit the same as an insurance discount?
No. The IRS describes a separate credit for home battery storage, and it does not change your insurance premium.
If your renewal notice raised questions, or storm season has you worried about your roof, windows, or a planned battery, you don’t have to sort it out alone. Our team can look at the whole picture with you, including the roof, the windows and doors, and the battery setup you’re considering. Book a free first consultation: it is confidential and carries no obligation to continue. Consulta inicial gratuita, confidencial y sin compromiso. Contact ASP Superhome.
Why Homeowners Plan Ahead
Insurers set their own terms
Each insurance company decides whether and how it offers a discount for solar battery backup. Review the details with your insurer before you plan around any savings.
Records make the conversation clearer
Installation contracts, invoices, equipment specifications, permit and inspection records, and the installation date are the details most often requested.
Battery backup adds resilience
A solar battery can keep key systems running during outages, which is one reason many South Florida homeowners consider it alongside their solar panels.
Planning with our team
Our team can walk you through the installation, the documentation you will need, and how the system is set up for your home.
A Quick Note on Discounts
Insurance discounts and premiums depend on your insurer, your policy, and your home. ASP Superhome does not set insurance rates, so keep your installation records organized and confirm the details before making decisions based on expected savings.
Documents to Gather
Installation contract or invoice
Keep the signed agreement and final invoice for your solar battery system in one place.
Equipment specifications
Note the battery model, capacity, and related solar equipment details.
Permit and inspection records
Permit approvals and inspection results show how the system was installed.
Installation date
Record the date the battery backup was completed so your insurer has an accurate timeline.


