


Impact Doors | South Florida
A Shattered Sliding Glass Door: What Your Insurance May Cover
Coverage depends on what caused the damage and what your policy says. Here is how to think it through, and how to get a replacement door that stands up to the next storm.
By Jonathan Rodriguez · Published October 24, 2026
Considering a new sliding glass door? Our impact doors are one option to explore, and our team offers a free first consultation that is confidential and without obligation. Your homeowners policy, the cause of the break, and your deductible all shape the answer. No one can promise a payment from general information alone. This guide explains each piece in plain terms for South Florida homeowners.
The Short Answer
Yes, a shattered sliding glass door may be covered when a sudden, covered event breaks it. Coverage usually depends on what caused the break and what your policy says about that cause. Florida’s homeowners insurance guidance explains that coverage depends on the policy form and on covered or excluded perils.
Sudden, accidental damage is treated differently from slow wear. Your policy’s covered perils (the named causes of loss it pays for) and its exclusions (causes it leaves out) draw the line. Your deductible matters too. If the repair bill is smaller than the deductible, you may pay the whole cost yourself.
If your sliding glass door broke and you're weighing repair or replacement while the claim is still open, we'd be glad to talk it through with you. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Why Sliding Glass Doors Shatter
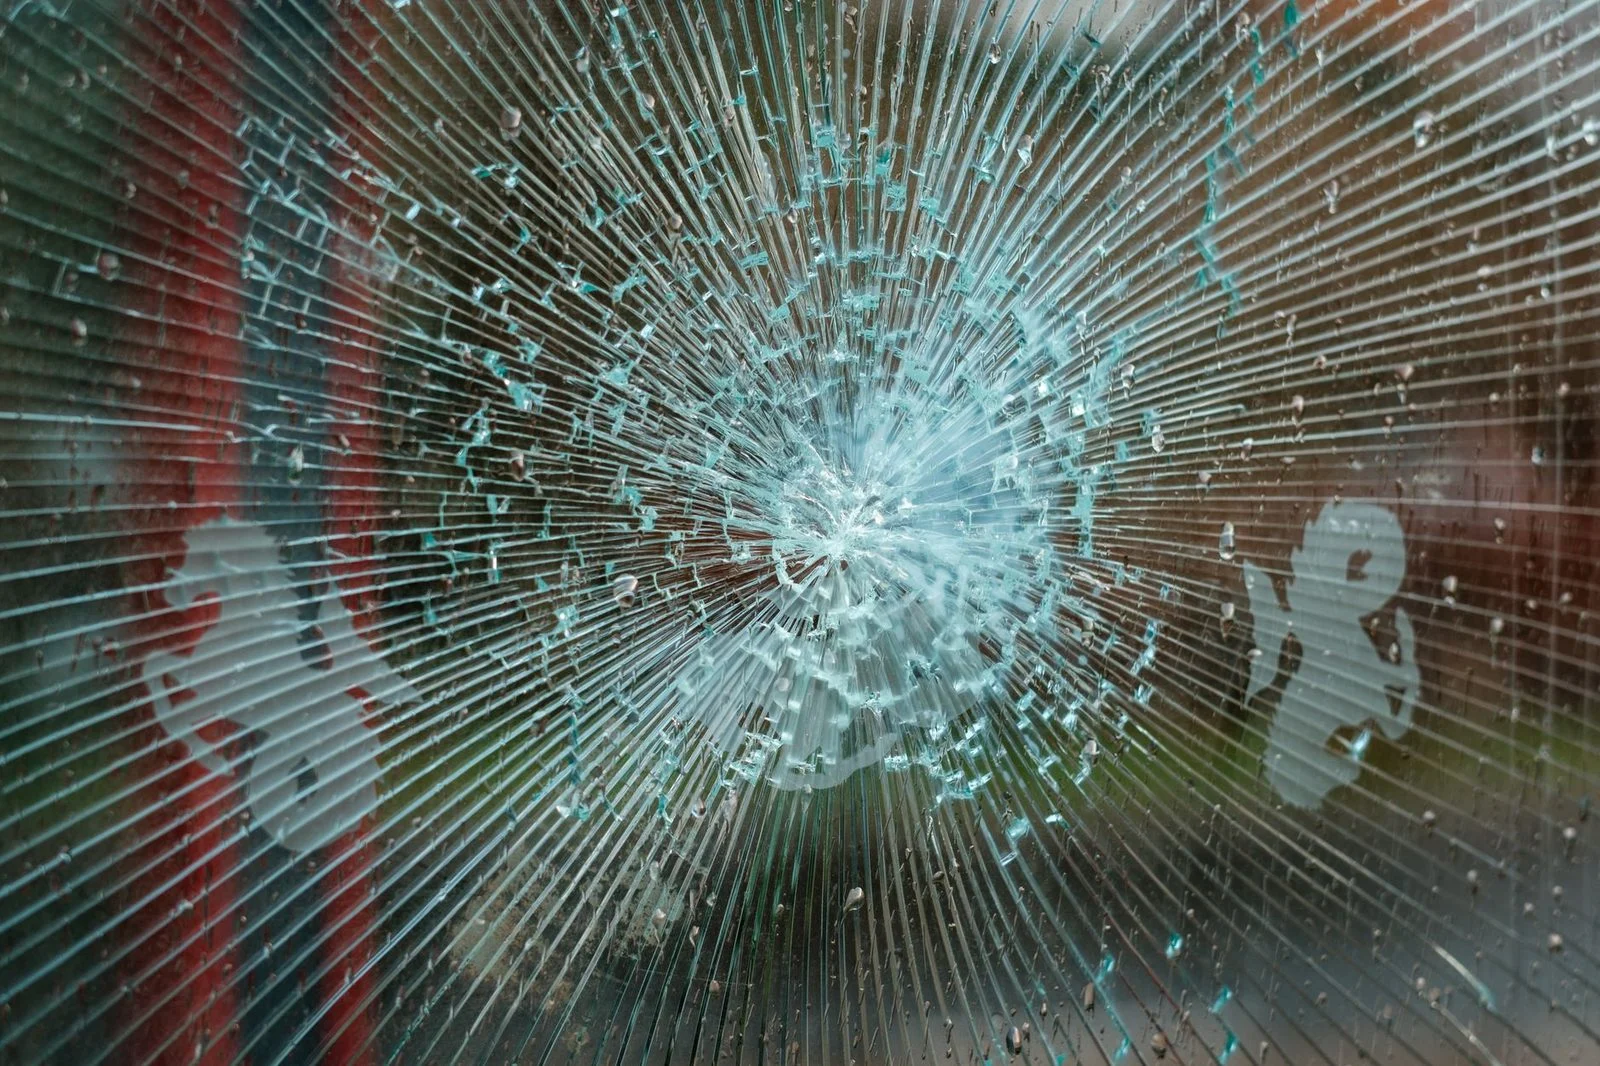
Sliding glass doors are often made of tempered glass. Tempered glass is built to break into many small pieces. That’s why a shattered panel can look like total destruction, even when the frame is still sound.
Common causes include:
- A thrown object, or a yard tool such as a lawn mower or weed trimmer, striking the glass
- A child, pet, or adult running into the door
- A break-in or attempted break-in
- Storm debris blown against the door
Other causes work differently. Thermal stress, manufacturing flaws, and seal or frame wear over the years are often treated as maintenance or warranty matters. The cause is the first thing an insurer will look at. Write it down early, while you still remember it clearly.
Does Homeowners Insurance Cover a Broken Sliding Glass Door?
Yes, when a sudden, covered event causes the break, many homeowners policies respond. A thrown rock or a falling tree limb is a common example of sudden impact. Vandalism and break-ins may also be covered, and a police report often helps show that cause.
Damage that builds up over time is commonly excluded. Weather exposure, poor installation, and lack of upkeep usually fall into that group. Coverage can reach the glass, frame, and track when a covered event damages them. How far it reaches depends on your policy wording.
A mower striking the door is a question many people ask. Whether that is covered depends on the policy’s peril language and any exclusions that apply. Ask your insurer to explain how its peril language applies to your situation.
How Your Policy Terms Shape the Claim
Start with replacement cost. Under Fla. Stat. § 627.7011, for a dwelling insured on a replacement-cost basis, the insurer must first pay at least the actual cash value of the loss, less any deductible. It pays the remaining amounts as repairs are done and costs are incurred.
Actual cash value means value after depreciation, or wear over time. An older door may therefore receive less at first. Ask how your policy calculates that figure before you choose a replacement type.
Law and ordinance coverage matters when building rules change. The same statute says extra costs to meet applicable laws and ordinances may be limited to 25 or 50 percent of the dwelling limit, as the policyholder selects. Many policies also restore a door to a similar type rather than upgrade it, so an impact product may cost more than the claim pays.
Hurricane and Windstorm Damage in South Florida
Wind-driven debris often breaks sliding doors during storms in Miami-Dade, Broward, Palm Beach, Collier, and Lee counties. Storm losses can carry a separate hurricane or windstorm deductible. That deductible can be higher than your standard one, so check the figure in your policy before you plan costs.
Timing matters. Under Fla. Stat. § 627.70132, a claim is barred unless notice was given to the insurer in accordance with the policy within 1 year after the date of loss. A supplemental claim for additional loss from the same peril must be noticed within 18 months. The statute also sets limited exceptions, such as tolling for certain servicemembers.
For hurricanes, the date of loss is the date that the hurricane made landfall; for tornadoes, windstorms, severe rain, or other weather-related events, it is the date the event is verified by the National Oceanic and Atmospheric Administration. For tornadoes, windstorms, severe rain, and other weather-related events, the date of loss is the date the National Oceanic and Atmospheric Administration verifies the event. Don’t wait. The notice clock starts running from that date.
Storm claims often involve more than one item. Document the door alongside roofing, screens, and window damage. Products sold as storm protection are also regulated. Under Fla. Stat. § 553.8425, products or systems of construction must demonstrate compliance with the structural windload requirements of the Florida Building Code through one of the listed methods, such as a certification mark, a test report, or a product-evaluation report.
What to Do Right After the Glass Breaks
Safety comes first. Keep people and pets away from the opening. Clear broken pieces with thick gloves and a stiff broom. Avoid walking barefoot near the area.
Next, limit weather and entry. Cover the opening with plywood or heavy cardboard, or tape a sheet over it. Miami-Dade County’s hurricane guidance on windows and doors covers securing openings. Keep receipts for any temporary materials, since they may matter to the claim.
Before anything is moved, photograph the door, frame, track, and surrounding area from several angles. Note the time and cause of the break. Write down the names of any witnesses.
Then contact your homeowners insurer promptly. Report the loss and ask what documentation it needs. If a break-in is suspected, file a police report and keep the report number in your claim file.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Impact Glass as a Replacement Choice
Standard tempered glass and impact-rated glass respond differently to debris and forced entry. Impact-rated glass is built to resist wind-borne debris. That is why it comes up so often after storms.
Replacing with impact glass can cost more than like-kind replacement. That added cost may fall outside the claim unless a law and ordinance provision or an endorsement applies. Ask your insurer how it treats the difference before you sign a contract.
Fit matters too. Frame, track, and hardware compatibility decide whether a new unit works in the existing opening. Cost depends on door size, glass type, frame material, and installation conditions. An on-site look is the most reliable way to estimate a specific door.
Key Takeaways
- Coverage depends on the cause of the break, your policy’s terms, and your deductible.
- Safety, securing the opening, and documenting the damage come before any claim decision.
- Notice deadlines run from the date of loss, so report promptly.
- Impact-rated replacement may improve storm and security performance, but the added cost may fall outside the claim.
Frequently Asked Questions
Is a shattered sliding glass door covered by insurance?
It often can be, when a sudden covered event such as a thrown object, a storm, or a break-in causes it. Your policy wording decides the answer.
How long do I have to report the damage?
Under Florida law, a claim is generally barred unless you give notice within 1 year after the date of loss.
Does insurance pay for impact glass?
It may pay for a like-kind replacement. The extra cost of impact glass may fall outside the claim unless a specific provision applies.
If your sliding glass door broke and you’re weighing repair or replacement while the claim is still open, a free first consultation with ASP Superhome is confidential and comes with no obligation to continue. We can talk through the practical options for your home.
Why Homeowners Choose Impact Doors After a Break
Built to Withstand Impact
Impact-rated sliding doors are designed to resist flying debris and forced entry, so a replacement can be stronger than the door it replaces.
Clear Written Estimates
We provide a detailed estimate for your replacement door, so you can compare the scope of work with your insurance records.
Confidential First Consultation
Your first consultation is free, confidential, and comes with no obligation to continue.
A Local Team
Our team serves homeowners across South Florida, from Miami and Fort Lauderdale to Boca Raton, Naples, and Fort Myers.
Don't Leave the Opening Unprotected
A shattered slider can leave your home open to weather, pests, and intruders. Secure the area as best you can while you gather your information, and keep photos of the damage before any cleanup.
Preparing for Your Replacement
Document the Damage
Take clear photos of the broken glass, frame, and track, and note the date and what you believe caused the break.
Review Your Policy
Look at your coverage for windows and doors, and any wording about storms, debris, or break-ins.
Get a Written Estimate
Ask for a detailed quote that lists the door type, impact rating, and installation, so you have clear figures to work from.


